Free Guide · VA Loan Buyers
You've earned this benefit.
Here's how it works
in San Antonio.
What eligible veterans, service members and surviving spouses should know about the VA loan: eligibility, entitlement, the funding fee, what makes a VA offer strong, and how assumability works.
Get the Free Guide ↓Quick Answer
A VA loan lets eligible buyers purchase a home with no down payment, as long as the price doesn't exceed the appraised value, and with no private mortgage insurance. This free guide explains who qualifies, how entitlement works, what the funding fee is and who's exempt, and how to put together a strong VA offer in San Antonio. Written by Tiffany Reed, MRP-certified REALTOR®, who has used the VA loan benefit more than once herself.
Funding fee rates can change. Check current rates at VA.gov. Data current as of October 2026.
Send me the free guide.
Share your name and email below for your free copy of the VA guide. Unsubscribe whenever you like.
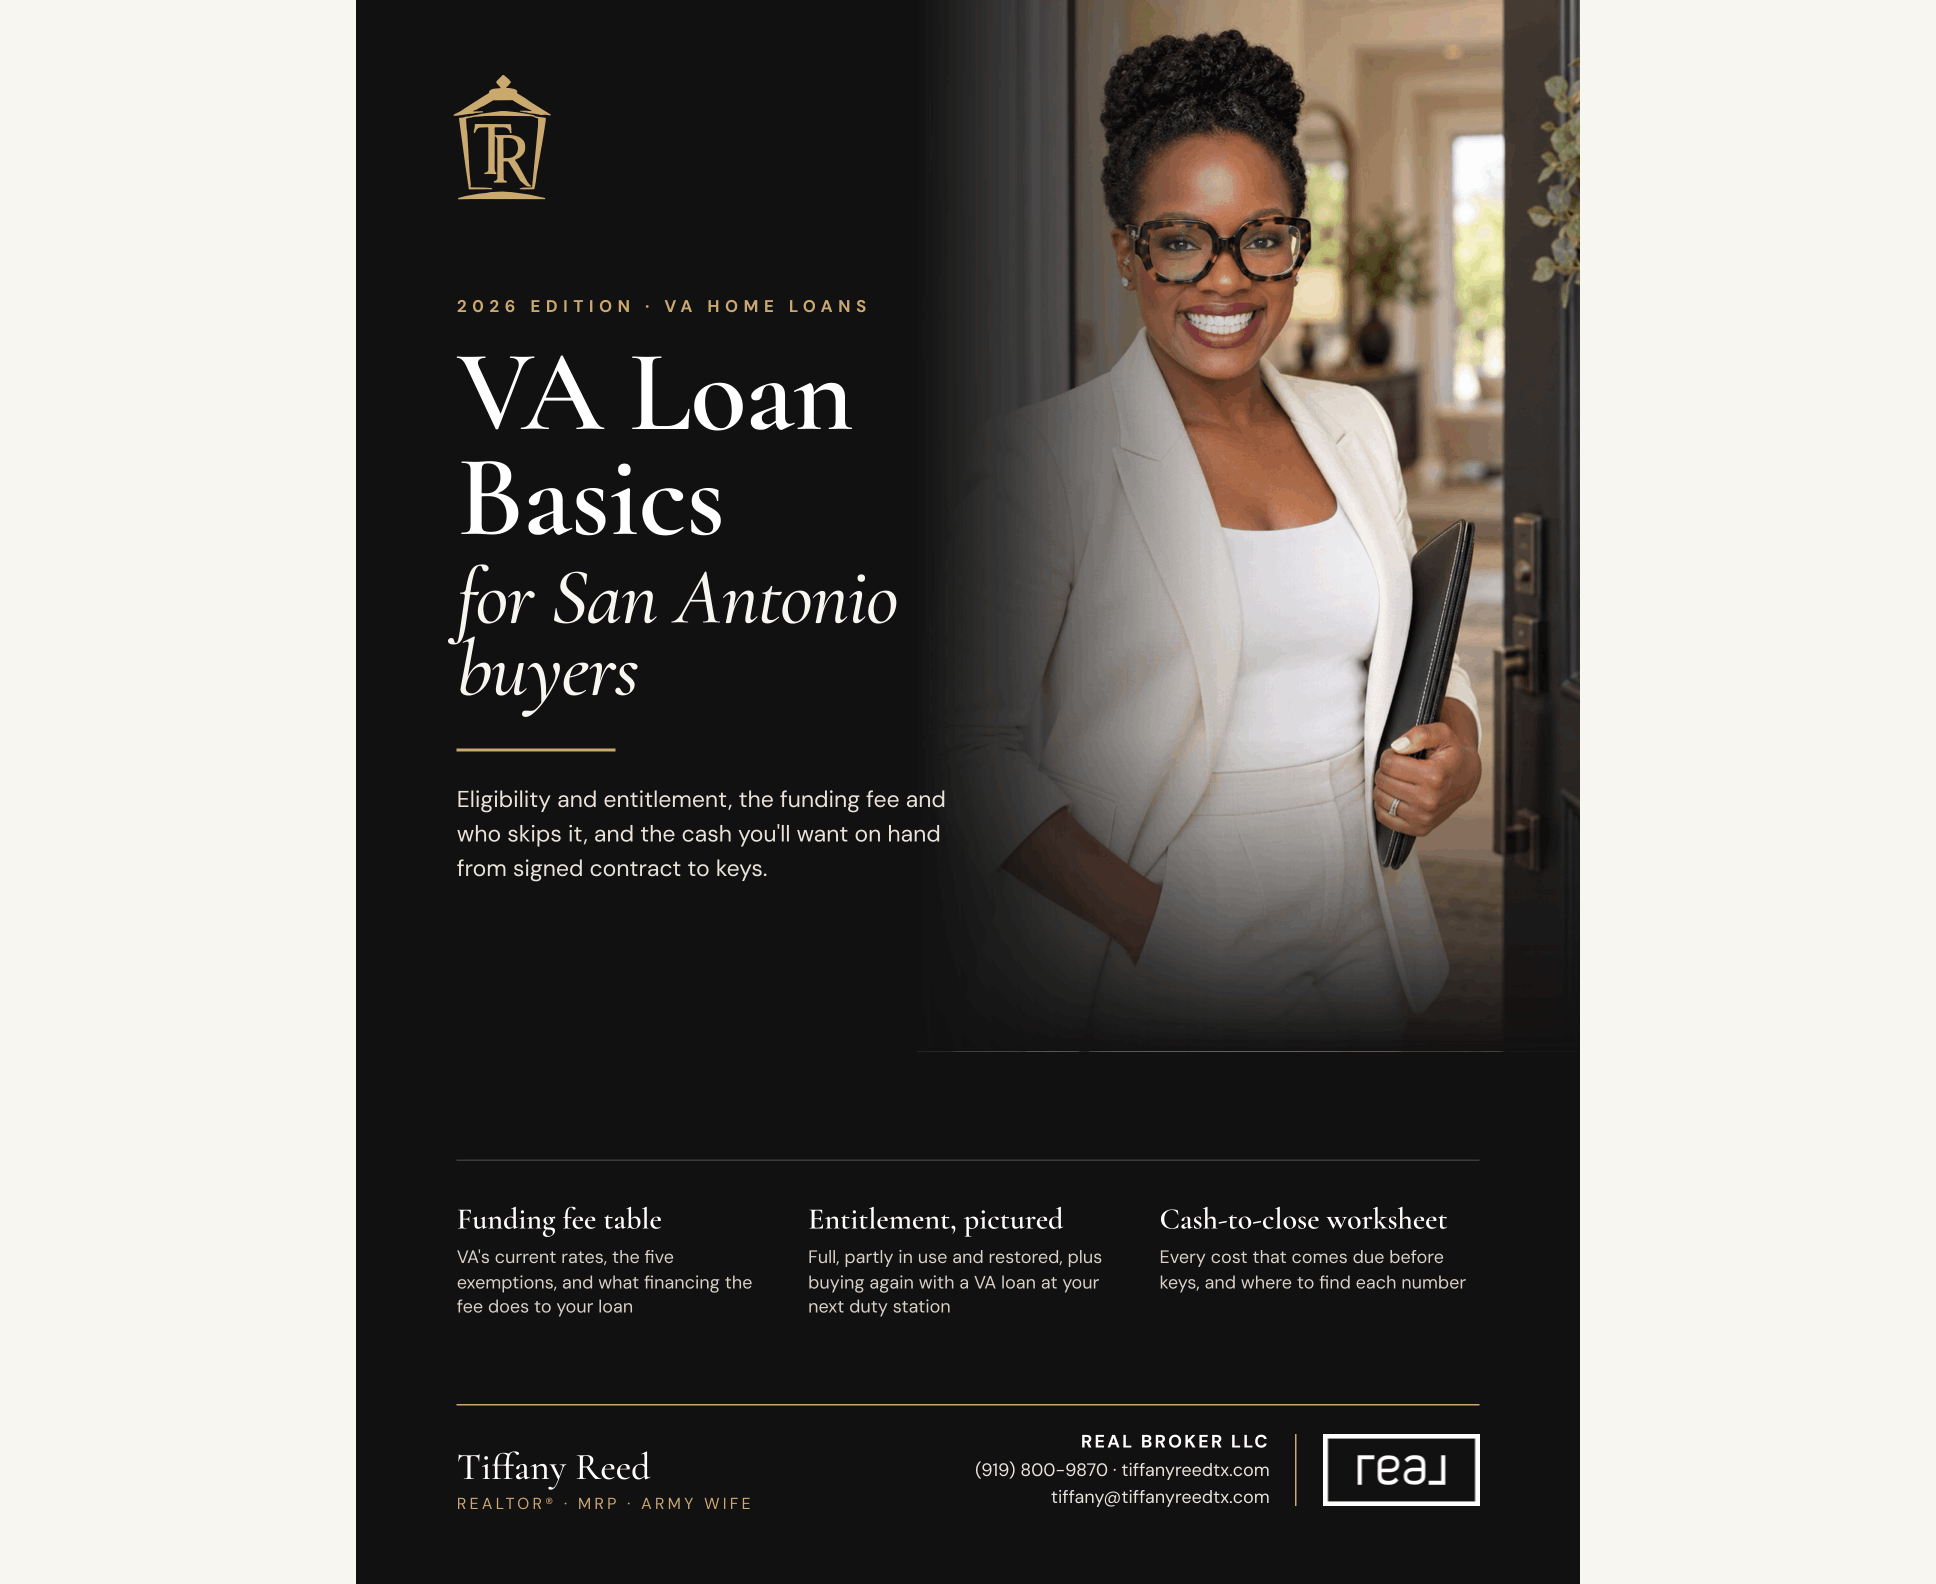
VA Loan Basics Guide, 2026 Edition
Key Takeaways
What the VA loan
actually gives you.
- Eligible service members, veterans and surviving spouses can buy with no down payment, as long as the sales price doesn't exceed the appraised value.
- A VA loan has no private mortgage insurance (PMI), which conventional loans usually require with less than 20% down.
- The one-time VA funding fee can be paid at closing or financed into the loan.
- You don't pay the funding fee if you receive VA compensation for a service-connected disability, receive Dependency and Indemnity Compensation (DIC) as a surviving spouse, or fit one of the other exempt categories VA lists.
- You can use the benefit more than once. Entitlement is typically restored after you sell the home and pay off the loan, and VA allows a one-time restoration if you pay off the loan but keep the home.
- Your lender can usually pull your Certificate of Eligibility (COE) online through VA's system, so you don't need to get it yourself first.
- A qualified buyer can assume a VA loan at its existing rate with the servicer's approval, and in some cases VA's. Unless that buyer is a veteran who substitutes their own entitlement, the seller's entitlement stays with the loan until it's paid in full.
Data current as of October 2026 · Sources: VA.gov purchase loans · VA.gov funding fee · VA.gov COE · VA Buyer's Guide · VA Circular 26-23-10
About This Guide
Your VA benefit can do
more than you might think.
You can use it more than once, it never carries PMI, and a future buyer may be able to take over your rate. Still, the same questions come up every time: Do I have entitlement left? Do I owe the funding fee? What does the VA appraisal look for, and how do I write a strong offer? This guide answers them for San Antonio's market.
For the full buying process with a VA loan, see my VA loans page. If you'd like to talk through your situation before you're ready to start, I'm glad to answer questions: Let's Talk About Your Next Move.
What's Inside
What does the VA loan
guide cover?
- What a VA loan is and who qualifies: service requirements and the Certificate of Eligibility, which your lender usually pulls for you
- How entitlement works, including using the benefit again or using remaining entitlement
- The VA funding fee: what it is, how it's calculated, how it's paid, and who's exempt
- No down payment and no PMI: what that means for your monthly payment and long-term cost
- What makes VA buyers strong buyers, and how to write a clean VA offer in San Antonio
- VA loan assumability, and why it matters more when rates are higher
Ready for the full guide?
Send Me the Free Guide →Common Questions
What VA loan buyers ask
before they reach out.
What makes a VA offer strong in San Antonio?
A VA buyer has already met both VA's and the lender's standards for credit and income, and can buy with no down payment and no PMI. Sellers weigh the whole offer: price, closing date, repair requests and how solid the financing looks, so a strong pre-approval and clear terms put that strength on paper. The guide covers how to set one up.
Can I use my VA loan benefit more than once?
Yes. The VA loan benefit isn't one-time use. How it works depends on your entitlement. If you've sold the home from a previous VA loan and paid the loan off, your entitlement is typically restored. If you've paid the loan off but kept the home, you can request a one-time restoration. And if you still own a home with a VA loan on it, you may have remaining entitlement for another purchase. The guide walks through entitlement in detail.
What is the VA funding fee and how much is it?
The VA funding fee is a one-time fee paid to the Department of Veterans Affairs. It lowers the program's cost to taxpayers, since VA loans don't require a down payment or monthly mortgage insurance. It's a percentage of the loan amount, and the percentage depends on the type of loan, whether it's your first VA loan, and how much you put down. Some borrowers are exempt, including veterans receiving VA compensation for a service-connected disability and surviving spouses receiving DIC. You can pay the fee at closing or finance it into the loan. Check current rates at VA.gov.
What is VA loan assumability and why does it matter?
A VA loan is assumable, which means a future buyer of your home may take over your loan at your original interest rate, subject to approval and the buyer's financial qualification. When market rates are higher than yours, a low-rate assumable loan can make your home more appealing to buyers. The trade-off: if the buyer isn't an eligible veteran who substitutes their own entitlement, your entitlement stays with the loan until it's paid off, which can limit your next VA purchase.
Do I need a special lender or agent to use my VA loan?
You need a lender that makes VA-backed loans. It also helps to have an agent who knows how the VA appraisal and its minimum property requirements fit into the contract timeline. The VA loans page walks through the process from start to finish.
Data current as of October 2026 · Sources: VA.gov funding fee · VA Buyer's Guide · VA Circular 26-23-10 · VA Lenders Handbook, Ch. 12
Tiffany Reed, REALTOR® | MRP | Real Broker LLC
(919) 800-9870 | tiffany@tiffanyreedtx.com | tiffanyreedtx.com